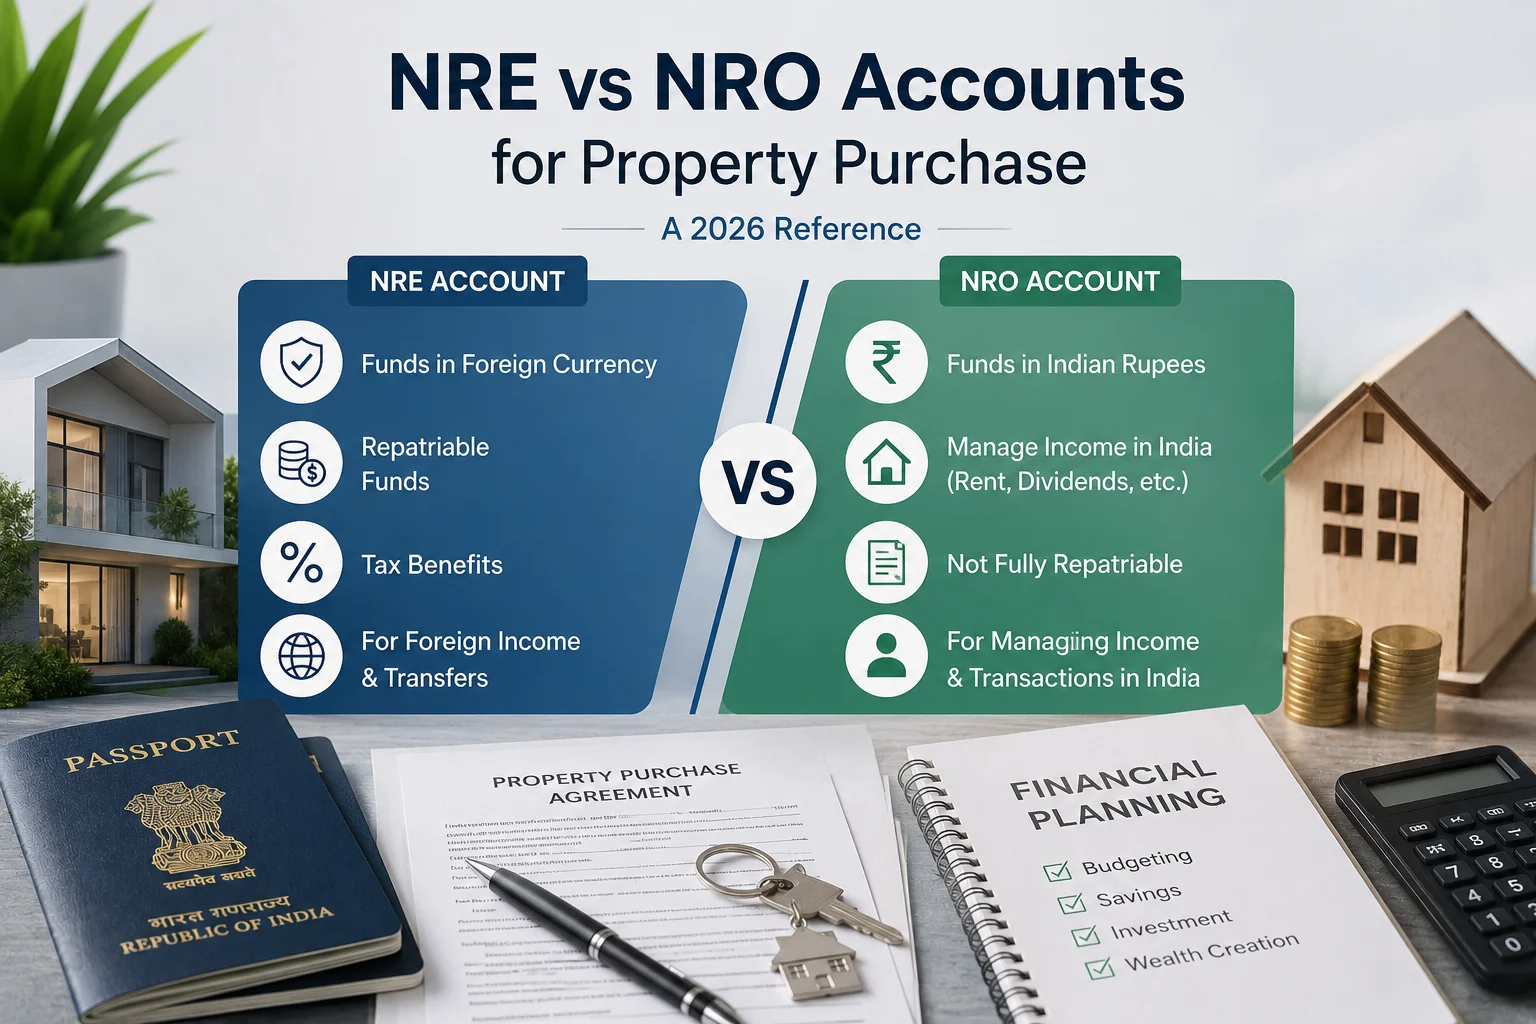
NRE (Non-Resident External) accounts hold foreign-earned income remitted to India in INR. NRO (Non-Resident Ordinary) accounts hold Indian-earned income such as rental income, dividends, or pension. For NRI property purchase, NRE is often the cleaner channel for repatriability, but both can fund a property. The choice depends on the source of funds and the eventual exit strategy.
What each account is
NRE Account
- Holds foreign income remitted to India.
- Fully repatriable subject to applicable regulations.
- Interest is generally tax-exempt in India.
- Intended for income earned outside India.
NRO Account
- Holds income generated within India.
- Used for rental income, pension, dividends, and other India-source receipts.
- Subject to applicable repatriation rules and limits.
- Interest is taxable in India.
Repatriation differences
Funds in an NRE account are essentially foreign earnings transferred into India. Regulations generally allow easier movement of these funds back overseas.
NRO funds are treated differently because they originate from Indian sources. Repatriation is possible but involves additional compliance procedures and documentation.
For NRIs who expect to eventually sell a property and transfer funds overseas, the funding route chosen at purchase can significantly affect future convenience.
Tax treatment of interest
NRE account interest is generally exempt from Indian income tax while the account holder qualifies as a non-resident under applicable rules.
NRO account interest is taxable in India and may be subject to TDS.
Tax treatment should always be verified with a CA because regulations and individual circumstances can differ.
Funding a property purchase
Both NRE and NRO accounts can be used for property purchases in India.
The decision usually depends on three factors:
1. Source of funds
Foreign earnings generally move through NRE accounts.
Indian-earned income generally moves through NRO accounts.
2. Repatriation goals
Buyers planning future repatriation often prefer NRE funding where feasible.
3. Tax planning
Interest treatment and compliance requirements differ between account types.
Joint accounts and Power of Attorney
Both NRE and NRO accounts can involve joint-holding structures subject to banking regulations.
Power of Attorney arrangements are also possible for routine account operations. However, specific restrictions may apply to fund transfers and repatriation activities.
Always confirm account-operating rules directly with the bank.
Common mistakes
- Using a regular resident savings account after becoming an NRI.
- Mixing foreign-earned and Indian-earned funds without proper structuring.
- Assuming repatriation works the same for both account types.
- Ignoring tax implications before property purchase.
- Not consulting the bank’s NRI desk before transferring large sums.
Which account is better for property purchase?
The answer depends on the buyer.
NRE may suit:
- NRIs funding property entirely from overseas income.
- Buyers expecting future repatriation.
- Investors looking for simpler overseas fund movement.
NRO may suit:
- NRIs using rental income generated in India.
- Buyers using pension or dividend income received in India.
- Individuals already maintaining substantial India-side financial activity.
Many NRIs ultimately maintain both accounts and use them for different purposes.
Frequently asked questions
Can I have both NRE and NRO accounts?
Yes. Many NRIs maintain both.
Can both accounts be used to buy property?
Yes. Subject to FEMA and banking regulations, both can be used for property transactions.
Which account is better for future repatriation?
NRE is generally considered more straightforward for repatriation purposes.
How long does account opening take?
Usually one to four weeks, depending on the bank and country of residence.